Home Insurance in Marion, OH: Coverage, Costs and Quote Questions
What a Marion, Ohio home policy covers, what moves the price, and the basement, river and older-home questions to ask so your quote fits your house.
Guides to the questions Ohio families and business owners actually ask: the 25/50/25 minimum, uninsured drivers, sump pumps and sewer backup, roof claims, rental properties and long-term care. From an independent agency in Marion and Powell.
or call (740) 387-8335
This blog will cover Ohio insurance the way we explain it across the desk: home guides on rising renewals, roof claims, snow and ice liability and break-ins; the Ohio water problems that cause the most claims, sump pump failure and sewer backup; auto guides on the 25/50/25 minimum, uninsured motorist coverage, tickets, accidents and rideshare driving; asset-based long-term care; flood, renters, landlord and life insurance; and business guides for Ohio practices and small businesses. Every guide is written by eGoodwin Insurance, an independent agency in Marion and Powell serving Ohio since 1990, and reviewed by Mark Goodwin. When you're ready for real numbers, call (740) 387-8335 and we'll compare several of the companies we represent.
No guides match that search yet. Try a different word, or request the topic and we'll put it on the calendar.
Rising renewals, roof claims, snow and ice, break-ins and the coverage gaps Ohio homeowners find out about too late. Start with the guides below.
What a Marion, Ohio home policy covers, what moves the price, and the basement, river and older-home questions to ask so your quote fits your house.
Rebuilding costs, storm claims and your own home all push Ohio home insurance premiums. See what drives a renewal increase and what you can still control.
Storm damage to a roof is often covered; old age and wear usually aren’t. Learn how roof deductibles and payouts work so a claim holds no surprises.
A slip on your icy walk, a snow-loaded roof or a burst pipe: see what Ohio home and landlord policies typically cover so you can plan before winter.
A yearly safety check for Ohio homes: smoke and CO alarms, an escape plan, extinguishers, the kitchen and basement water. Fewer surprises and claims.
What Ohio homeowners insurance pays after a break-in: stolen items, damage, limits on valuables and how to file. Plus simple ways to lower your risk.
What an Ohio homeowners policy covers and excludes, how premiums are set, and the questions to ask before you buy or renew.
Why your dwelling limit should match the cost to rebuild, not the market value, and how to check yours.
Sump pump failures, sewer backup, frozen pipes, ice dams and spring storms are the claims Ohio homeowners actually call about. Here's what's covered and what isn't.
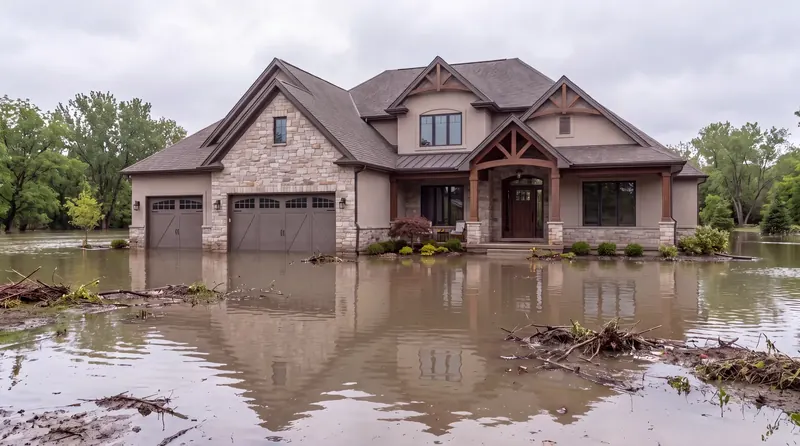
Most Ohio home policies exclude sewer backup and sump pump overflow unless you add a water backup endorsement. Learn what it covers and how to set the limit.
What home insurance pays when pipes freeze and burst, and the steps that keep a winter claim from being denied.
Wind, hail, tornadoes and power surges: how Ohio home policies respond to storm season.
Flood, sewer backup or seepage? Why the source of the water decides whether a basement claim is covered.
How ice dams form, what roof and interior damage a policy may cover, and how to prevent the next one.
How percentage wind and hail deductibles work, with the math in real dollars.
Ohio requires 25/50/25 and leaves uninsured motorist coverage optional. These guides cover what that means for your household, from rates and tickets to rideshare and college drivers.
Ohio’s 25/50/25 minimum, why uninsured motorist coverage matters, what Ohio drivers pay on average and how to compare quotes at the same limits.
Ohio doesn't require uninsured motorist coverage. Learn what UM/UIM pays, how Ohio's offset works and how to set limits that protect your family.
What goes into an Ohio car insurance rate: driving record, age, ZIP, car, credit and your coverage choices, plus the levers you control to pay less.
You can't haggle an Ohio car insurance rate, but an independent agent can change the company, coverage, deductibles and discounts behind it.
Step-by-step: what Ohio law expects at the scene of a crash, what to document, how to report the claim, and how repairs and rentals work.
How Ohio BMV points work, what 12 points means, and how a ticket can affect your car insurance, plus practical steps to limit the damage.
Ohio law lets personal auto policies exclude rideshare driving. Learn where the coverage gaps are and how an endorsement can close them.
Should your college student stay on your car insurance? What to tell your agent when they take a car to school, leave it home or drive yours.
Ohio's 25/50/25 minimum explained, plus proof of insurance and why the legal minimum is rarely enough.
Asset-based (hybrid) long-term care combines life insurance or an annuity with care benefits. These guides explain how it works and how to plan for it in Ohio.
How asset-based (hybrid) long-term care works in Ohio: care benefits, a death benefit, 1035 funding and Partnership questions, so you can plan with confidence.
Hybrid vs. traditional long-term care: premiums, benefits and what happens if you never need care.
What long-term care costs in Ohio and how to plan for it without draining savings.
How a life insurance policy with a long-term care rider pays for care while you're living.
NFIP and private flood, the 30-day wait, flood zones and the difference between a flood and a sewer backup.
Ohio home policies don’t cover flood. Learn NFIP limits, the 30-day wait, private flood options and who needs coverage, so you’re covered before water rises.
What flood insurance covers that a homeowners policy doesn't, side by side.
Single-family rentals, small multifamily and growing portfolios: DP-1 vs. DP-3, loss of rents, vacancy and LLC-owned property.
How Ohio landlord insurance works: DP-1 vs DP-3, liability, loss of rents, vacancy, water backup and LLC titling, so every rental you own is covered right.
Insuring a growing rental portfolio: DP-3s, LLCs, umbrellas and when to move to commercial coverage.
What renters insurance covers, what it costs and how it works for college students and apartment renters across Ohio.
Does your home policy cover your student's dorm room? How the away-at-school limit works, when a student needs renters insurance and what to check.
What renters insurance covers in Ohio, what it costs, and what your landlord's policy never will.
How life insurance protects a household's income, mortgage and plans, and the financial risks families face most often.
The five events that most often derail Ohio family finances, from an early death to a lawsuit, and the coverage that helps your family stay on its feet.
Term, whole and how much coverage an Ohio family needs, in plain English.
Fraud prevention, Ohio BWC workers' comp, and coverage for dental and medical offices, med spas and small businesses.
Five internal controls that help Ohio small businesses prevent employee and outside fraud, plus the crime, bond and cyber coverage that can help you recover.
The coverage most Ohio small businesses need, from a BOP to cyber, and how it fits together.
How Ohio's state-run BWC workers' comp system works and where stop-gap coverage fits.
Practice, liability, cyber and benefits coverage for Ohio dental offices.
What Ohio medical practices need beyond malpractice: property, cyber, EPLI and more.
Coverage for Ohio med spas and aesthetic practices, including equipment and professional liability.
How independent agents differ from captive agents and buying direct, and how we compare the companies we represent.
Independent agent, captive agent or buying direct: how each works and what it means for your quotes.
The team at eGoodwin Insurance, an independent agency with offices in Marion and Powell that has served Ohio since 1990. Topics come from the questions clients ask us every week, and every guide is reviewed by Mark Goodwin before it goes live. When Ohio rules or the insurance market change, we update the guides to match.
No. These guides explain how Ohio insurance works and what people in similar situations tend to consider. Coverage that fits your home, cars and family takes a conversation. That conversation is free and starts at our quote page or (740) 387-8335.
No. We're an independent agency, so we compare coverage from several of the insurance companies we represent. The Ohio rules we write about, like the 25/50/25 auto minimum and the flood exclusion, apply no matter who insures you. Coverage is subject to each company's policy terms, conditions and availability.
Every topic on this page is on our publishing calendar, starting with fresh rewrites of the guides from our previous website. Bookmark this page, or call (740) 387-8335 if you have a question that can't wait.
Tell us about your home, your cars and your plans. We'll compare several of the insurance companies we represent and walk you through the options.