
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Maybe you just moved to a Westerville street off State Street and the new address changed what your renewal costs. Maybe your teenager is about to start driving the I-270 ramps, or your college student wants to keep a car on campus. Or maybe someone dinged your door in an Uptown lot and drove off, and you’d like to know what your policy does with that.
This page answers the car insurance questions we hear from Westerville drivers specifically. The statewide basics, like Ohio’s 25/50/25 liability minimum, optional UM/UIM and how proof of insurance works, live in our Ohio car insurance guide. Here we focus on what’s different about driving and garaging a car in Westerville.
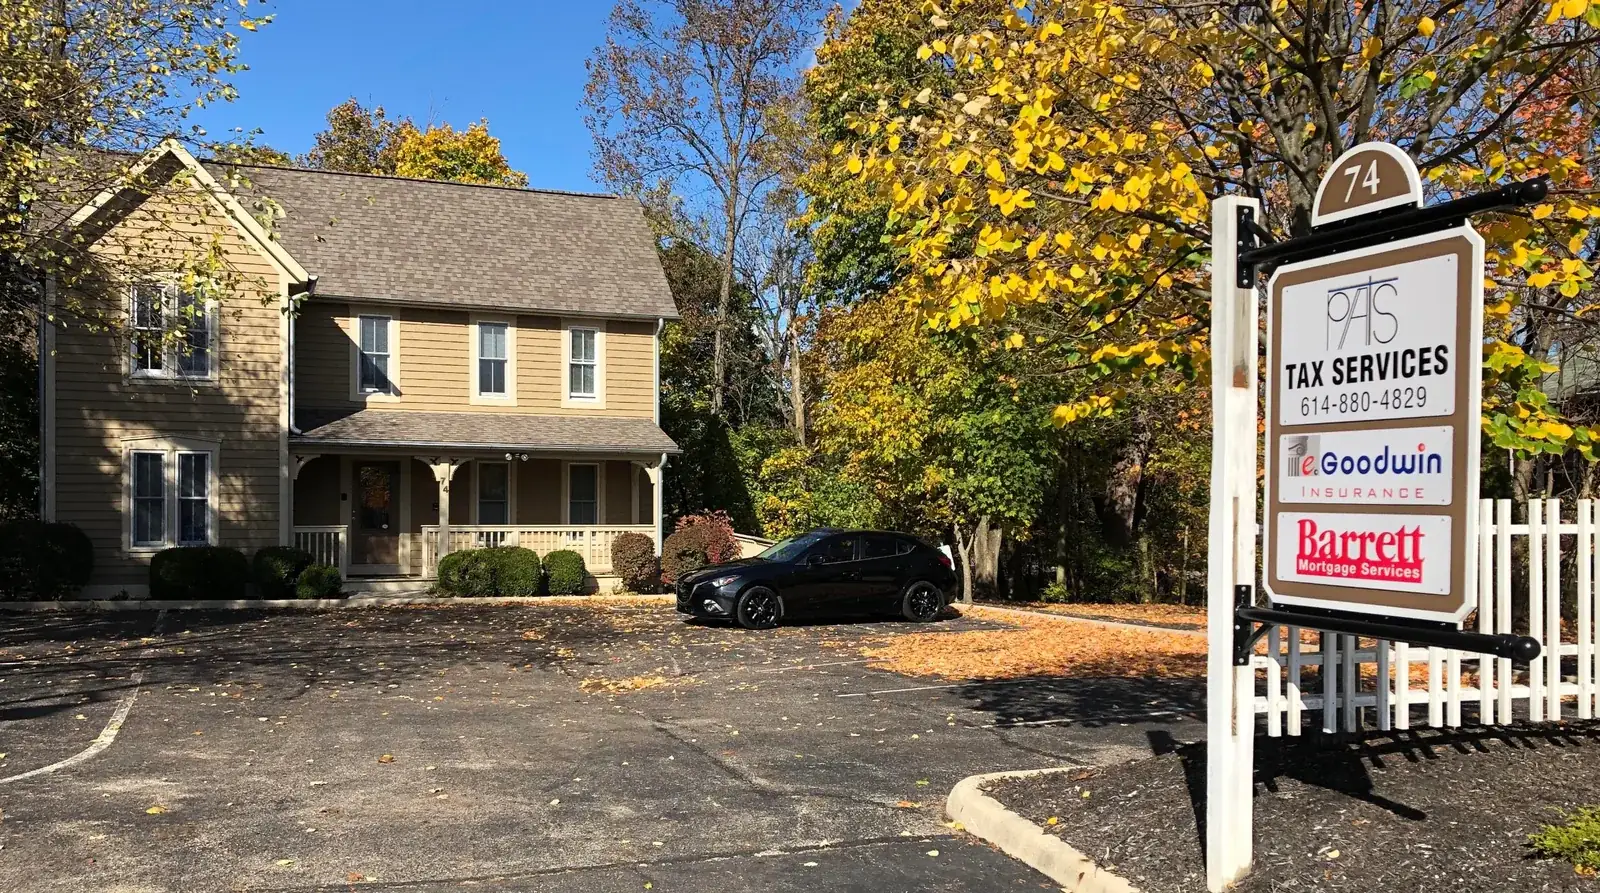
That means the I-270, I-71 and State Street corridors, the Franklin and Delaware County line, deer season, winter snow emergencies, Uptown parking, teen and college drivers and how we quote it all. We serve Westerville from our Powell office at 74 E. Olentangy Street, and we work for you, not an insurance company.
Which roads shape car insurance for Westerville drivers?
The short answer: Westerville sits on the north edge of Franklin County, where Interstate 270 was the county’s top crash route in 2025, so commute mileage, garaging address and liability limits matter more than any single statistic.
Most Westerville commutes touch a few big roads. I-270 runs along the south side of the city, I-71 runs to the west near Polaris, and State Route 3, which becomes State Street through town, carries traffic north and south through Uptown. Polaris Parkway, Schrock Road and Cleveland Avenue fill in the rest.
The Ohio State Highway Patrol’s Franklin County crash fact sheet, published October 2026 with 2025 data, puts numbers on that traffic. Interstate 270 was the county’s top crash route, with 1,739 crashes. U.S. Route 40 and Interstate 70 came next.
The same sheet lists the county’s top contributing factors. Failure to yield led with 4,085 crashes, followed by speed with 2,339. Distracted driving was tied to 654 crashes, and OVI to 1,200. Those are countywide figures, not Westerville’s, but they describe the roads Westerville drivers use every day.
How does that reach your premium? Not directly. Insurance companies don’t price you off a crash sheet. The Ohio Department of Insurance’s Automobile Insurance Guide says companies weigh where you live and how you use the car, including a long daily commute, along with your record and the car itself. Each company files its own rating plan and draws its own territories.
What we ask Westerville drivers about their commute
Where the car sleeps
Companies rate by the address where the car is kept most nights. Give the exact Westerville address, not a work or school address.
How far you drive
A daily I-270 or I-71 commute is rated differently from driving mainly around town. Give an honest annual mileage.
Work, pleasure or business
Commuting, pleasure and business use are separate ratings. Tell us if the car is used for deliveries or rideshare.
Tickets and claims
Your record follows you across companies. A ticket on State Street counts the same as one anywhere in Ohio.
One note on side jobs. Many personal auto policies limit or exclude coverage while you’re driving for a delivery app or rideshare service. If anyone in your household does that, even a few nights a month, tell us so we can check the policy wording and any endorsement the company offers.
Does it matter whether you live in the Franklin or Delaware County part of Westerville?
The short answer: Not for the coverage itself, because companies rate by your address and ZIP rather than the county name, but the county does decide which municipal court handles a transferred ticket and frames the local crash numbers you’ll read about.
Westerville sits on a county line, with parts of the city in Franklin County and parts in Delaware County. The city’s Mayor’s Court resource page notes that a case transferred from Westerville Mayor’s Court goes to the Franklin County or Delaware County Municipal Court, based on the county where the alleged offense occurred.
Your car insurance doesn’t change at the county line. Ohio’s minimums and optional coverages are the same everywhere in the state. What changes is the address and ZIP code your company rates, and two Westerville ZIP codes can price differently even a mile apart.
| If you live in | What the Patrol reports | What it means for you |
|---|---|---|
| Franklin County | Busier roads 94 fatal crashes in 2025, with I-270 the top crash route. | Your ZIP is rated by each company’s own territory map. Liability and UM/UIM limits deserve a careful look. |
| Delaware County | Fewer, often rural 13 fatal crashes in 2025, down from 19 in 2024; 8 were rural. | The same Ohio rules and the same address-based rating apply. Rural two-lane roads are a reminder to keep comprehensive. |
The two counties are very different in size, so the raw counts aren’t a fair comparison of how safe either one is. They do show why we don’t guess at a Westerville price from a county headline. We quote the actual garaging address.
How big a risk are deer for Westerville drivers, and what covers a deer hit?
The short answer: Deer are common in Westerville yards, parks and roadways, Ohio deer crashes peak from October through December, and hitting one is a comprehensive claim, so the deductible you pick is the number that matters.
The Westerville Division of Police’s wildlife page says residents often see deer in backyards, parks and crossing roadways. It adds that deer mate in the fall, when activity around homes and roads rises, and that one deer crossing usually means others are nearby. Its advice is simple: if you see a deer near the road, slow down.
Statewide, the numbers are large. The Ohio State Highway Patrol reported on November 1, 2025 that it had recorded 108,047 deer-involved crashes since the beginning of 2020, 48 of them fatal. The Patrol’s 2024 Deer Crash Bulletin shows when they happen.
Those hours line up with a Westerville commute in late fall, when it’s dark on the way to work and dark again on the way home. Roads that run along parks, creek corridors and open land are where we’d slow down first.
How a deer claim works
The Ohio Department of Insurance treats hitting a deer as a comprehensive loss, not a collision. With comprehensive, you pay your comprehensive deductible and the policy pays the rest of the covered repair. With liability only, the damage to your car is yours to pay.
Swerving changes things. If you miss the deer and hit a tree, a guardrail or another car, that’s usually handled as a collision claim, depending on the policy. The Patrol’s advice is to brake firmly, stay in your lane and not swerve, because swerving can lead to a more severe crash.
After a deer strike, the Patrol says to pull safely off the road, call 911 or the nearest Patrol post and stay away from an injured deer. Then photograph the damage and the scene, and call us at (740) 387-8335.
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
What should Westerville drivers know about winter driving and claims?
The short answer: Westerville plows its busiest roads first and asks drivers to keep cars off the street in storms, and in a slide-off your own damage is a collision claim while damage you cause to others falls under liability.
The city’s snow removal page explains the order of work. Crews start with the most highly traveled roads and the streets that serve hospitals. Next come streets around schools and the routes that carry traffic in and out of the city. Subdivision streets, courts, alleys and dead-ends come last.
The same page logged a real test in January 2026. After Governor DeWine declared a statewide emergency on January 24, Franklin County went to a Level 3 Snow Emergency on January 25, and the page reported Franklin and Delaware counties at Level 3 the next morning. Under Level 3, the page explains, roads are closed to non-emergency workers.
The city also asked residents to move vehicles off the street, especially on major and designated routes, so plows could get through, and warned that towing would be used when necessary. That’s practical advice for your car, too. A car left on a snow route is more likely to get boxed in or clipped.
Collision
Damage to your own car from hitting an object, or another car, is a collision claim after your deductible.
Liability
Their car and injuries fall under your liability coverage, up to your limits, if you’re found at fault.
Comprehensive
Falling objects, including ice-laden limbs, are generally comprehensive losses, not collision.
Usually not covered
Tow and impound fees after a parking violation generally aren’t a covered loss. Roadside assistance is a separate, optional add-on.
Two habits help before the first storm. Check the state’s OHGO app, which the city points to for road conditions, before you head for I-270. And make sure your collision deductible is an amount you could pay in January without stress. Our auto insurance page lists the optional coverages we can price, including roadside assistance and rental reimbursement.
What should you do after a crash or a parking-lot hit in Westerville?
The short answer: Call 911 if anyone is hurt, report minor no-injury crashes inside city limits to Westerville Police, get the free crash report online, and remember that a hit-and-run on your parked car is usually a collision claim on your own policy.
Westerville Police make the paperwork easier than most people expect. The department’s online reporting page lists minor traffic accidents among the incidents you can file online. It applies only when it isn’t an emergency, the incident happened inside city limits, there are no known suspects and no one was hurt.
If you can’t say yes to all four, the page says to call the department at (614) 882-7444 to speak with an officer. For an emergency, call 911. Once a report exists, the Records Bureau’s accident report portal lets you request it for free, and the city says most reports are available within 24 to 72 hours.
Uptown parking and parked-car damage
Uptown is where a lot of Westerville parking happens. The city’s smart parking page describes more than 360 sensor-equipped spaces in four public lots, labeled A through D, with a free app that shows open spaces in real time.
Tight lots and street parking mean door dings, scraped bumpers and mirrors clipped by passing traffic. Here’s how those claims usually sort out:
- The other driver stops or leaves a note. Their property damage liability should pay for your car. Get their name, insurance company and plate number.
- Nobody stops. Your own collision coverage usually pays, after your deductible. Without collision, the repair is generally yours.
- Someone breaks in or vandalizes the car. Damage to the car is generally a comprehensive claim. Belongings taken from the car usually fall under homeowners or renters insurance, not auto.
- You’re hurt by a driver who flees. Uninsured motorist coverage is built for hit-and-run injuries, which is one more reason we recommend keeping it.
Photograph the car where it sits, note the lot letter or street, and check whether a nearby business has a camera. Then file the police report and call us. We’ll tell you whether a small repair is worth a claim before you open one.
How should Westerville families insure teen drivers and college students?
The short answer: List every licensed driver in the household, know the Ohio probationary license limits on hours, passengers and phones, and tell the company where a student’s car is actually kept, because a missing driver or wrong address can cause trouble at claim time.
Young drivers are a big share of local crashes. The Patrol’s Franklin County fact sheet counted 2,811 crashes in its age 15-to-19 driver category in 2025 and 7,284 in its age 15-to-24 category. Statewide, it says unsafe speed contributed to 25% of fatal teen-driver crashes in Ohio and failure to yield to 14%.
Ohio law adds guardrails for new drivers. Under Ohio Revised Code 4507.071, in effect since July 1, 2015, a probationary license holder in the first 12 months can’t drive between midnight and 6 a.m. or carry more than one passenger who isn’t a family member, unless a parent or guardian is along.
After the first year, the hour limit narrows to 1 to 5 a.m. There are exceptions for work, school-sponsored events and official religious events with written documentation. A separate law, ORC 4511.205, bars probationary drivers, and permit holders under 18, from using a phone or similar device in any manner while driving, except hands-free navigation and emergencies.
What we’d set up for a Westerville teen
- Add the teen to the family policy first. ODI’s advice for new drivers is to start with your family’s agent. We’ll price your teen on your policy and show the alternatives side by side.
- Ask about good student and other discounts. ODI lists good student and multi-car discounts among the common ones. Each company sets its own rules.
- Raise liability before the teen drives. A new driver raises the odds of a claim. Higher limits, and often an umbrella, protect the household’s savings and home equity.
College students, including Otterbein students
Westerville is home to Otterbein University, and many families here also have a student at a campus elsewhere. If a student keeps a car at school, tell the company where it’s garaged and roughly how much it’s driven. If the student leaves the car at home and drives only on breaks, say that too. Either way, keep every licensed household member listed. A driver or car the company didn’t know about can cause problems when a claim comes in.
How much car insurance coverage should a Westerville driver carry?
The short answer: More than Ohio’s 25/50/25 minimum for most Westerville households, with uninsured and underinsured motorist coverage matched to your liability limits and an umbrella considered once you have home equity, savings or a teen driver.
Ohio’s legal floor is 25/50/25 liability under Ohio Revised Code 4509.51. In plain English, that’s $25,000 per injured person, $50,000 per crash and $25,000 for property damage. Our Ohio guide walks through a crash example showing how quickly those limits run out.
A Westerville household often has more to protect than the minimum covers. Home equity, retirement savings and future wages can all be reached by a lawsuit after a serious crash on I-270. We usually price two or three liability levels side by side, such as 100/300/100 and 250/500/100, so you can see each step in dollars.
That’s why we treat UM/UIM as essential, even though Ohio law makes it optional. It protects your own family when the other driver has no insurance or too little. ODI notes companies can’t sell you UM limits above your liability limits, so the two usually move together.
If your liability limits are already high, an umbrella adds a layer above both your auto and home policies. Our Ohio umbrella insurance guide explains the underlying limits companies usually require and how to size one.
How should Westerville drivers compare car insurance quotes?
The short answer: Quote every company at the same liability, UM/UIM and deductibles, with every driver and the exact garaging address listed, then compare what each policy pays before you compare price.
We don’t publish a Westerville “average” car insurance premium, because no honest one exists. The best public figure is statewide. The NAIC put Ohio’s 2023 average auto insurance expenditure at $947.24 a year, and our Ohio guide explains what that number does and doesn’t mean. Your Westerville quote can land well above or below it.
So we compare like for like. Here’s the order we work through with Westerville drivers:
- Bring your declarations page
It lists your drivers, cars, limits, deductibles and premium. It’s the baseline, so every change from it is on purpose.
- Give the exact garaging address
Use the Westerville address where each car is kept. For a student’s car, use where it actually stays.
- Set liability to what you own
Start from 25/50/25 and ask what 100/300/100 or higher would cost. Think about the equity and savings a lawsuit could reach.
- Match UM/UIM to your liability
With nearly one in five Ohio drivers estimated to be uninsured, this protects your own family. If you turned it down years ago, you can add it back.
- Keep comprehensive for deer season
Pick a comprehensive deductible you could pay in November. Then pick a collision deductible you could pay in January.
- List every driver and every use
Include teens, college students home on breaks and anyone who drives for a delivery app.
- Ask which discounts apply
Multi-car, good student, bundling and safety features can add up, depending on the company.
Bundling car and home insurance with one company may lower what you pay. If you own your Westerville home, our Westerville home insurance guide covers the home side, from water backup to the county line. Eligibility and discounts vary by company.
We quote the same coverage across our lineup of companies, then walk you through the differences in plain English. You can start an auto quote online, call us, or stop by the Powell office Monday through Friday, 9 to 5.
The bottom line
A Westerville auto policy comes down to a handful of local decisions. Carry liability limits that fit what you own, because the I-270 corridor is busy and the minimum runs out fast. Keep UM/UIM matched to your liability. Keep comprehensive for deer season, with a deductible you could pay. And list every driver and the real garaging address, especially for teens and students.
If you’d like a second set of eyes, send your ZIP below or call (740) 387-8335. We’ll read your declarations page with you, show what your limits would and wouldn’t pay, and quote the same coverage across the companies we represent, with your home policy too if you’d like to see a bundle.
Some clients have saved up to 36% when we re-shopped their coverage. Savings vary by household and aren’t guaranteed. You can also visit our Powell office, which serves Westerville, Dublin, Lewis Center and Delaware.
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Westerville car insurance FAQ
Does it matter for car insurance whether I live in the Franklin or Delaware County part of Westerville?
Not for the coverage itself. Ohio’s 25/50/25 liability minimum and its optional coverages, like UM/UIM and medical payments, are the same in both counties. What companies rate is your garaging address and ZIP code, using their own territory maps, so two Westerville addresses can price differently. The county does matter in other ways. The city says a case transferred from Westerville Mayor’s Court goes to the Franklin County or Delaware County Municipal Court, depending on where the offense occurred, and each county’s sheriff declares snow emergencies. Your tax bill or lease shows which county you’re in.
Does car insurance cover hitting a deer in Westerville?
Yes, if you carry comprehensive coverage. The Ohio Department of Insurance treats a deer strike as a comprehensive loss, not a collision, so you pay your comprehensive deductible and the policy pays the rest of the covered repair. With liability only, the damage to your car is yours. Westerville Police say deer often turn up in backyards, parks and roadways, and the Ohio State Highway Patrol says 47% of Ohio deer crashes from 2019 through 2023 happened from October through December. If you swerve and hit something else instead, that’s usually a collision claim, depending on your policy.
What should I do after a minor crash in Westerville?
Make sure everyone is safe and call 911 if anyone is hurt. Exchange names, insurance companies and plate numbers, and photograph both cars and the scene. Westerville Police let you file some minor traffic accidents online, but only when it isn’t an emergency, it happened inside city limits, there are no known suspects and no one was injured. Otherwise, call the department at (614) 882-7444. The city says most crash reports are available within 24 to 72 hours through its free online portal. Then call your agent before you agree to any repair plan.
What driving limits apply to a teen with a probationary license in Westerville?
Ohio’s rules apply statewide. Under Ohio Revised Code 4507.071, a probationary driver in the first 12 months can’t drive between midnight and 6 a.m. or carry more than one non-family passenger unless a parent or guardian is along, and after the first year the hour limit narrows to 1 to 5 a.m. There are documented exceptions for work, school events and religious events. A separate law, ORC 4511.205, bars probationary drivers from using a phone in any manner while driving, except hands-free navigation and emergencies. A first violation carries a $150 fine and a 60-day suspension.
Is damage to my parked car in Uptown Westerville covered?
Usually, if you carry the right coverage. If the other driver stops or leaves a note, their property damage liability should pay for your car. If no one stops, your own collision coverage usually pays after your deductible, and without collision the repair is generally yours. Vandalism to the car is generally a comprehensive claim, while belongings taken from the car usually fall under homeowners or renters insurance. File a police report, photograph the damage where the car sits and note the lot or street. The city says its four public Uptown lots hold more than 360 spaces.
How do I get a car insurance quote for a Westerville address?
Start with your current declarations page, your driver’s license numbers and the exact Westerville address where each car is kept. Then quote every company at the same liability limits, the same UM/UIM and the same deductibles, with every driver listed, including teens and college students. Mention any tickets or claims up front so the price doesn’t change later. eGoodwin Insurance serves Westerville from our Powell office at 74 E. Olentangy Street, and we quote the same coverage across our lineup of companies. Call (740) 387-8335, Monday through Friday from 9 to 5, or start online.
Last reviewed by Mark Goodwin on .