
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Maybe you just bought a brick house a few blocks from Ohio Wesleyan and the lender wants proof of insurance before closing. Maybe you’re in one of the newer neighborhoods at the edge of town and your first renewal came in higher than you expected. Or maybe the March 2024 tornado south of town made you wonder what your policy would actually do with a torn-off roof.
This guide covers home insurance in Delaware, Ohio: the city that serves as the Delaware County seat, not the state of Delaware. Statewide basics, like the six parts of an HO-3 policy, replacement cost versus actual cash value and the Ohio FAIR Plan, live in our Ohio homeowners insurance guide. Here we stick to what’s different about a house in Delaware.
We serve Delaware homeowners from our Powell office at 74 E. Olentangy Street, and our Marion office is just up US-23 to the north. We’re an independent agency, so we quote your home across our lineup of companies, and we work for you, not an insurance company.
What kinds of homes are in Delaware, Ohio, and why does that matter for your policy?
The short answer: Delaware mixes 19th-century homes near downtown with a large share of houses built since 2000, and each group raises different questions about rebuild cost, roof terms and basements.
Delaware is growing fast. The Ohio Department of Development’s 2025 Delaware County profile lists the city at 46,521 residents in 2024, up from 41,712 in 2020. The city’s own fast facts page says its population has almost doubled since 2000. That growth shows up as new subdivisions around the edges of town, while the blocks near downtown still hold homes built a century or more ago.
| Measure | City of Delaware | Delaware County |
|---|---|---|
| Owner-occupied share of occupied homes | 64.7% | 78.2% |
| Median value of owner-occupied homes | $318,400 | $419,500 |
| Homes built 2000 or later | — | 48.8% |
| Homes built 1939 or earlier | — | 7.3% |
| Median year built | — | 1999 |
Two numbers stand out. The city’s median home value sits below the county’s, and a bigger share of its homes are rented. Both fit a city with an older core, a university next to downtown and newer neighborhoods growing outward.
Why it matters: your price and your coverage depend on the house, not just the ZIP code. The Ohio Department of Insurance’s homeowners insurance guide lists the age, construction and condition of the home among the factors companies use, along with your coverage amounts, deductibles and claims history.
If you own a newer home
A newer house is often easier to place, and ODI lists a newly built home among the discounts some companies offer. The mistake we see most is a dwelling limit set at the purchase price. That price includes the lot and the neighborhood. Your dwelling limit should reflect what it would cost to rebuild the house today, including the finished basement, upgraded kitchen or three-car garage.
If you finished the basement after closing, tell your agent. It raises your rebuild cost and changes how much water backup coverage makes sense, which we cover below. ODI’s guide notes most policies expect you to insure at least 80% of replacement cost, or even a partial claim can pay less.
How should you insure an older home near downtown Delaware or Ohio Wesleyan?
The short answer: Insure an older home for what it would cost to rebuild with its real materials, ask about ordinance or law coverage, and check whether the roof settles at replacement cost or actual cash value.
Downtown Delaware is listed on the National Register of Historic Places, and the city’s Architectural Standards for Downtown Delaware (Ordinance 21-41, effective June 28, 2021) cover a Downtown Historic District that includes a residential subdistrict. Under those standards, city staff and the Historic Preservation Commission review proposed exterior work and new construction in the district.
That matters after a fire or a bad storm. The standards call for residential windows of wood or clad wood, and where historic windows can’t be repaired, replacements must keep the original profile and size. Roofing in the residential subdistrict is limited to materials such as slate, standing-seam metal, asphalt shingles and wood or composite shakes. Matching those details can cost more than standard builder-grade materials.
A few other checks for an older Delaware home:
- Rebuild cost first. Plaster walls, trim, built-ins and brick can make an older home cost more to rebuild than it would sell for. A current replacement cost estimate beats last year’s number.
- Updates on record. Many companies ask when the roof, wiring, plumbing and heating were last updated. Have the years handy before you quote.
- Roof settlement. Some policies pay an older roof at actual cash value, which subtracts depreciation. Our state guide walks through the replacement cost versus actual cash value math.
- Detached garages and carriage houses. Coverage for other structures is often a share of the dwelling limit. Check it if your lot has an older detached building.
Is your Delaware home at risk from the Olentangy River, and do you need flood insurance?
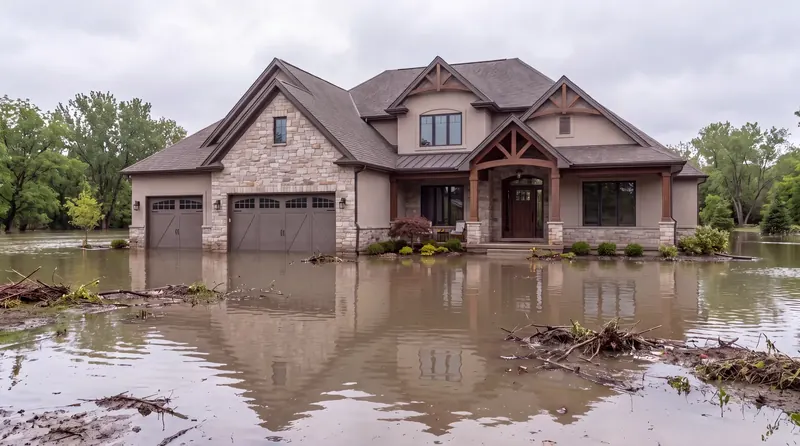
The short answer: Homeowners policies don’t cover flood, the Olentangy has flooded Delaware before, and the way to know your mapped risk is to look up your exact address on FEMA’s flood maps.
The Olentangy River runs right through Delaware, and the city has a long memory of it. In the March 1913 flood, the river crested at 27.5 feet, Delaware County lost 41 bridges, including every bridge through the city, and 18 people died, according to the Silver Jackets 1913 flood history hosted by the Midwestern Regional Climate Center.
Today, the City of Delaware appears on FEMA’s flood map index as National Flood Insurance Program community 390148. FEMA issued preliminary updated flood maps for Delaware County and its cities and villages in April 2022. To see the map that applies to your address, and whether any preliminary change affects it, search the FEMA Flood Map Service Center.
Smaller streams matter too. Delaware Run flows through the middle of town to the Olentangy, and a home doesn’t have to sit beside the river to take on water in a heavy storm. FEMA says about one-third of NFIP claims from 2013 to 2023 came from outside high-risk flood areas.
If your lender required flood insurance at closing, you already know you’re in a mapped high-risk area. If it didn’t, that isn’t the same as no risk. A lower-risk zone can also mean a lower flood premium, which is a good reason to price it before the next wet spring.
Does a Delaware homeowners policy cover a wet basement or a sewer backup?
The short answer: A sudden burst pipe is usually covered, but drain backup and sump pump overflow usually aren’t unless you add a water backup endorsement, and rising surface water needs flood insurance.
Basements are where a lot of homeowners find out what their policy actually says. ODI’s Severe Weather Toolkit says water backup in the basement isn’t typically covered and must be added, and that sewer and drain backup is excluded or limited in most policies. That one endorsement is often the difference between a paid claim and a cleanup bill.
| Where the water came from | Usually handled by | What to check |
|---|---|---|
| A pipe or water heater fails suddenly | Your homeowners policy, after the deductible | Freeze rules if the home sits empty in winter |
| A drain backs up or the sump pump overflows | A water backup endorsement, if you added one | Its limit compared with the cost of redoing a finished basement |
| Surface or river water flows in | A separate flood policy | The 30-day wait on a new NFIP policy |
| Groundwater seeps through walls over time | Usually not covered | Grading, gutters, downspouts and sealing |
If your basement is finished, size the backup limit to what it would cost to redo it: drywall, flooring, the furnace and water heater if they sit down there, and the furniture. Endorsement limits vary by company, and some start well below what a finished basement costs.
A few low-cost steps help on both sides of a claim. A battery backup on the sump pump covers the power outages that come with spring storms, and a water sensor can catch a leak early. Some companies credit protective devices, so ask. For a problem with a public sewer or storm line, the city’s Public Utilities Department takes calls at 740-203-1900.
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
How do tornadoes, hail and fallen trees play out on a Delaware homeowners claim?
The short answer: Wind, hail and falling trees are usually covered after your deductible, but a percentage wind/hail deductible can make a storm claim cost far more out of pocket than you expect.
Central Ohio storms aren’t abstract here. On March 14, 2024, an EF1 tornado with estimated peak winds around 110 mph touched down about three miles south of Delaware near US-23, according to the preliminary survey from the National Weather Service in Wilmington. Its path ran 35.6 miles across Delaware and Licking counties. Many homes lost siding and roofing, and many trees were snapped or uprooted.
Usually covered
Torn shingles, stripped siding and broken windows from wind are typically covered after your deductible.
Covered, read the roof terms
Whether the roof settles at replacement cost or actual cash value can matter more than the deductible.
Covered when they hit something
ODI says a tree falling on your home, garage or fence typically triggers repairs and tree removal. Debris removal may be limited if it hit nothing.
Not covered
Storm water that rises and flows into the house is flood, which needs its own policy.
Read the deductible line twice
ODI’s toolkit says many policies carry a separate wind/hail deductible, written as a flat dollar amount or as a percentage of the insured value. The percentage version is easy to underestimate on a newer, larger home.
- A kitchen fire would carry the $1,000 deductible.
- A wind claim after a tornado would carry 1% of $420,000, or $4,200.
Street trees deserve a word. In new Delaware subdivisions, street trees are planted in the tree lawn, which is part of the public right-of-way, under the city’s street tree planting standards (Public Works, 2018 edition), with species chosen by the City Shade Tree Commission. If a tree lawn tree looks like a threat to your house, call the city before you or a contractor touches it.
What if you rent out a house near Ohio Wesleyan, or rent one yourself?
The short answer: A homeowners policy is written for a home you live in, so a rental house generally needs a landlord or dwelling policy, and the tenants need their own renters policy for their belongings.
Delaware has a bigger rental market than the county around it: about 35% of occupied homes in the city are renter-occupied, going by the Census figures above. Ohio Wesleyan University, chartered in 1842 with about 1,300 students, sits on more than 200 acres next to downtown, according to the city’s fast facts. If you own a rental here, or are thinking of buying one, the insurance looks different from a homeowners policy.
A landlord policy, often written on a DP-3 dwelling form, covers the building, lost rent after a covered loss and your liability as the owner. It doesn’t cover the tenants’ belongings. Our landlord and rental property page explains the forms, and it’s worth reading before you sign a first lease.
If you rent in Delaware, your landlord’s policy covers the building, not your furniture, laptop or liability. A renters policy fills that gap. A college student may have some coverage under a parent’s homeowners policy, depending on the policy terms, so ask before assuming.
If you own several rentals or have teen drivers at home, an umbrella policy adds liability protection above your home and auto limits for the rare claim that goes past them.
How do you get a home insurance quote in Delaware, Ohio from an independent agent?
The short answer: Bring your declarations page and the basics about the house, and we’ll quote the same limits, deductibles and endorsements across our lineup of companies so the prices compare fairly.
We quote Delaware homes from our Powell office, and our Marion office sits up US-23 to the north. Both are open Monday through Friday from 9 to 5, and most of a quote can be handled by phone or email. Here’s the order we work in:
- Start with your declarations page
It shows your dwelling limit, deductibles, endorsements and premium, so every change from it is on purpose.
- Set the dwelling limit to rebuild cost
Use a current replacement cost estimate, not the purchase price or the county auditor’s value.
- Look up your flood zone
Search your address on FEMA’s Flood Map Service Center and decide on flood coverage before you need it.
- Size water backup to your basement
A finished basement needs a limit that matches what it would cost to redo it.
- Decide on mine subsidence
In Delaware County, insurers must offer it, and the rule caps the yearly premium at $20.
- Put every deductible in dollars
Line up the all-perils deductible and any wind/hail percentage across every quote.
- Ask which discounts you qualify for
ODI lists bundling home and auto, alarm systems, a newly built home and a claims-free history among them.
Mine subsidence surprises people, so a word on it. Under Ohio Administrative Code rule 3901-1-48 (effective February 14, 2022), Delaware County is one of 11 counties where insurers must offer mine subsidence coverage on an optional basis. It pays up to your dwelling limit or $300,000, whichever is less, with a deductible between $250 and $500. In plain English: your company has to offer it, it’s inexpensive, and you decide.
Bundling your home with your auto policy may lower what you pay, though eligibility and discounts vary. When the quotes come back, we lay them side by side and walk you through roof terms, backup limits and deductibles before price. You can also start on our home insurance page or request a free home quote online.
The bottom line
Home insurance in Delaware, Ohio is the same Ohio policy with local questions layered on top. For an older home near downtown, it’s rebuild cost, materials and ordinance or law. For a newer home, it’s a dwelling limit that tracks rebuild cost and a backup limit that fits the finished basement. Everywhere in town, it’s flood, a wind/hail deductible you could pay tomorrow and a yes or no on mine subsidence.
If you’d like a second set of eyes, call (740) 387-8335 or stop by our Powell or Marion office. We’ll read your declarations page with you, flag the gaps and quote the same coverage across the companies we represent.
Some clients have saved up to 36% when we re-shopped their coverage. Savings vary by household and aren’t guaranteed.
By clicking Get My Free Quote, I give Goodco LLC (eGoodwin Insurance) and its licensed agents my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (740) 387-8335 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Delaware, Ohio home insurance FAQ
Is Delaware, Ohio in a flood zone?
Parts of it are. The City of Delaware is a National Flood Insurance Program community, and FEMA’s flood maps show flood hazard areas along the Olentangy River and other streams in Delaware County. Whether your home sits in one depends on the exact address, so look it up on FEMA’s Flood Map Service Center. FEMA released preliminary updated maps for the county in April 2022, so check for changes too. Even outside a mapped zone, FEMA says about one-third of NFIP claims from 2013 to 2023 came from outside high-risk areas, and homeowners policies don’t cover flood.
Do I need mine subsidence coverage in Delaware County, Ohio?
It’s your choice. Under Ohio Administrative Code rule 3901-1-48, effective February 14, 2022, Delaware County is one of 11 counties where insurers must offer mine subsidence coverage on an optional basis, while 26 mostly eastern and southeastern counties get it automatically. If you add it, the coverage pays up to your dwelling limit or $300,000, whichever is less, with a deductible between $250 and $500. The rule caps the yearly premium at $20 in optional counties. Ask whether your policy includes it, and decide on purpose.
Does homeowners insurance cover sewer backup in a Delaware, Ohio basement?
Usually not, unless you add it. The Ohio Department of Insurance’s Severe Weather Toolkit says water backup in the basement isn’t typically covered and must be added, and that sewer and drain backup is excluded or limited in most policies. A water backup endorsement covers water that backs up through a drain or overflows a failed sump pump, up to its own limit. If your basement is finished, pick a limit that fits what it would cost to redo it. Water that flows in from outside is flood, which needs a separate policy.
How much does home insurance cost in Delaware, Ohio?
There isn’t one reliable price for the city, because every company rates the house, not just the ZIP code. The Ohio Department of Insurance lists the main factors: the home’s age, construction and condition, your coverage amounts and deductibles, distance to fire protection, and your claims and credit history. A newer home in a subdivision and a century-old brick house near downtown can price very differently. The fair way to compare is to quote every company at the same dwelling limit, deductibles and endorsements, then read the roof terms before price.
Do I need a landlord policy for a rental house near Ohio Wesleyan?
Usually, yes. A homeowners policy is written for a home you live in. If you rent the house to students or anyone else, you generally need a landlord or dwelling policy, often a DP-3, that covers the building, lost rent after a covered loss and your liability as the owner. It won’t cover your tenants’ belongings, so many landlords ask tenants to carry renters insurance. If you’re moving out and keeping the house as a rental, tell your agent before the tenants move in.
Does an older home in Delaware’s historic district cost more to insure?
It can, mostly because of rebuild cost. Plaster, trim, brick and original windows cost more to replace than standard materials, and the city’s Architectural Standards for Downtown Delaware call for wood or clad-wood windows and limit roofing materials in the residential subdistrict. Your dwelling limit should reflect that rebuild cost, not the sale price. Ordinance or law coverage helps pay for required code upgrades after a covered loss, and the Ohio Department of Insurance notes it may need to be added. Updated wiring, plumbing, heating and roofing may also help with eligibility and price.
Last reviewed by Mark Goodwin on .