Home / Renters Insurance

Ohio Renters Insurance: You don't own the building. You own everything in it.

Your landlord's policy covers their walls. Yours covers your things and your liability. Whether you rent near Ohio State, in Delaware or in Marion, we shop several carriers and help you set it up right.

HO-4The Renters Policy Form
4Core Coverages
5.0On Google (88 Reviews)
Since 1990Serving Ohio
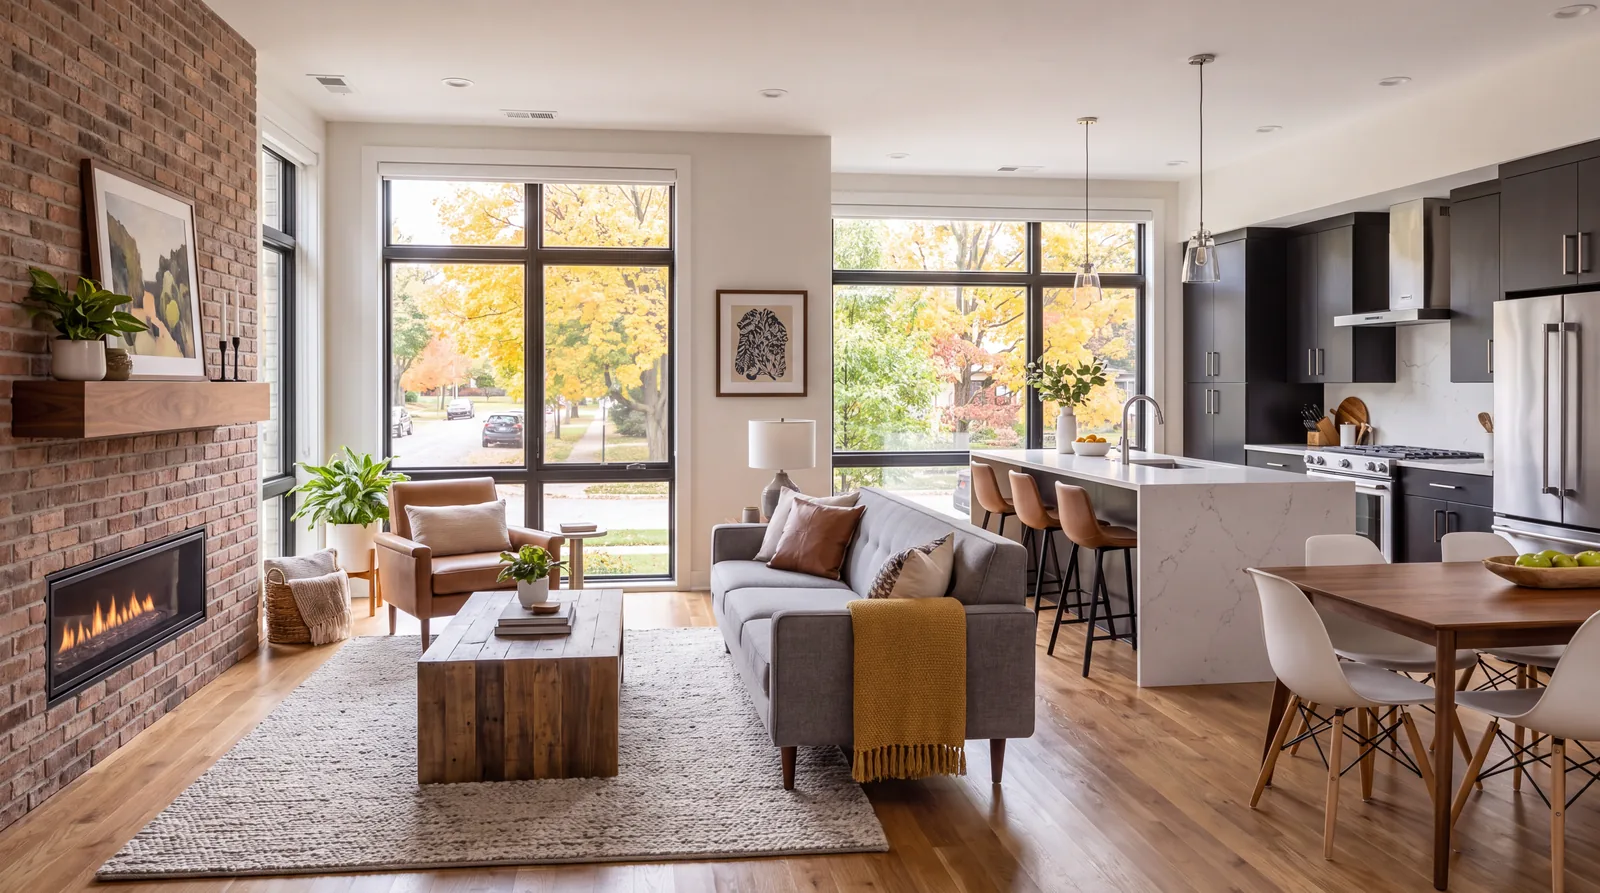
A bright, modern apartment living room
The Quick Answer

No state law makes you carry renters insurance, but your lease probably does, often with a minimum liability limit and the landlord listed as an interested party. A renters (HO-4) policy covers four things: your belongings (including things stolen from your car, which auto insurance doesn't cover), loss of use if your unit becomes unlivable after a covered loss, personal liability and medical payments for guests. Your landlord's policy covers the building only, never your belongings or your liability. Roommates need their own policies. In Ohio, common renters losses include severe thunderstorms, hail and wind, burst pipes in winter freezes, apartment fires and basement water from a sewer backup or failed sump pump, which is usually covered only with a water backup endorsement. Flood is excluded, but a contents-only flood policy may be available. Bundling renters with auto may lower what you pay. eGoodwin Insurance is an independent agency in Marion and Powell, Ohio. We shop multiple carriers for renters in Columbus, Delaware, Marion and across Ohio. Call (740) 387-8335.

Required by
Your lease, if anything
Landlord's policy
Covers the building, not your things
Basement water
Needs a water backup endorsement
Call first
(740) 387-8335
Ohio Renters Insurance, The Short Version

One of the most affordable policies in insurance. And plenty of renters skip it.

A lot of Ohio rents. Ohio State students in off-campus apartments around Columbus, young professionals in Dublin and Westerville, families renting houses in Delaware and Marion. Yet plenty of renters carry no policy at all. Usually it's because it feels like something for people with more stuff, or because the landlord surely has it covered. Neither holds up when something actually happens.

Here's the honest math. Walk through your place and add up what it would cost to replace everything at today's prices: the mattress, the couch, the desk, every screen, the kitchen, the closet, the bike. Most people are surprised by their own list. A renters policy protects all of it, and it's typically one of the most affordable policies you can buy.

Then there's the part nobody mentions: liability. Your policy isn't really about your couch. It's about the day your bathtub overflows into the unit below, or your dog bites someone at the park, or a friend gets hurt in your kitchen. Those can turn into serious bills with your name on them, and they're why your lease asks for coverage in the first place.

One more thing: bundling renters with your auto policy may lower what you pay. Discounts vary, so we won't promise a number. As an independent agency, we shop your coverage across several carriers and show you the real figures side by side.
Four coverages. And the things people assume are covered but aren't.

A renters policy, technically an HO-4, does four jobs. The exclusions are just as worth knowing as the coverages.

Coverage C
Your belongings

Personal Property

Everything you own, and it travels with you: your belongings are covered in your unit, in your car, at the gym and on vacation. Jewelry, watches and similar items usually have lower sub-limits, so anything valuable should be scheduled separately.

Coverage D
Real rent

Loss of Use

Pays for somewhere to live when your unit is unlivable after a covered loss. If you've been in the same place a while, today's rents may be higher than yours, so this limit deserves a real look.

Coverage E
Your liability

Personal Liability

The real reason your lease asks for this. It covers you when you injure someone or damage their property, like the overflowing tub into the unit below, plus legal defense. It follows you off the property too.

Coverage F
Guest injuries

Medical Payments

Pays a guest's minor medical bills regardless of fault, no lawsuit needed. It's a small coverage that settles the kind of thing that could otherwise turn into a liability claim against you.

Add-on
Basements

Water Backup

Water that comes up through a floor drain from a sewer backup, or in because a sump pump failed, is usually excluded unless you add a water backup endorsement. If you rent a basement unit or keep things in the basement, ask us about it.

Not covered
The walls

The Building Itself

Roof, plumbing, structure and common areas belong to your landlord's policy. Their policy covers their property and does nothing for yours. This is the assumption that costs people the most.

Not covered
Roommates

Your Roommate's Stuff

A standard policy covers you and a spouse or domestic partner. A roommate on the same lease isn't covered by your policy. Everyone needs their own, which also means nobody's claim uses up someone else's limit.

Not covered
Slow leaks

Gradual Leaks, Mold & Pests

Renters insurance is built for sudden, accidental losses. A slow drip under the sink, the mold that grows from it and pests are maintenance problems, not claims. Report leaks to your landlord in writing the day you notice them.

Not covered
Flood

Flood

Rising water from outside needs separate coverage. Heavy rain can push creeks and rivers like the Olentangy and Alum Creek out of their banks, and a contents-only flood policy may be available for renters. Water from inside the building, like a pipe that bursts in a hard freeze, is generally covered.

Not covered
Your car

The Vehicle Itself

The car is your auto policy's job, including hail damage, which falls under comprehensive. But what was inside the car when the window was broken is a renters claim. The two policies work together, which is why bundling them makes sense.

Need proof of insurance before you sign the lease?

We can add your landlord or property manager as an interested party and send proof of coverage straight to them.

Coverage Basics

Four things worth getting right on an affordable policy.

It's affordable enough that most people buy the first thing they're offered. These choices separate a policy that works from one that just exists.

1. Replacement cost, not actual cash value

This may be the most important line on a renters policy. Replacement cost pays what it takes to buy a new equivalent today. Actual cash value pays what your stuff is worth used, after depreciation. For example, an older laptop might be worth $300 used but cost $1,400 to replace.

Replacement cost usually costs a bit more, and it can make a big difference at claim time. If your current policy pays actual cash value, that's the first thing we'd look at.

2. Liability, sized to the damage you could cause

Many renters stick with whatever minimum the lease asks for, and that can be thinner than it sounds. One overflowing tub in a stacked apartment building can damage several units. A dog bite claim can get expensive fast.

Raising your liability limit often costs relatively little for the extra protection. If you have savings or a growing income to protect, ask us whether an umbrella policy makes sense on top of your renters and auto.

3. Water backup and loss of use

Ohio has a lot of basements and a lot of sump pumps. When a heavy storm overwhelms the sewer or the power goes out and the sump stops, water can come up through the floor drain. Standard policies usually exclude that unless you add a water backup endorsement. If you live in a garden-level unit or store things in a shared basement, it's worth adding.

Loss of use pays the gap between your normal housing cost and what you're forced to spend after a covered loss. An apartment fire can close a whole building, not just one unit, and finding a comparable place on short notice usually means paying today's rents. We'll check that your limit reflects what your area actually costs now.

4. Scheduling the things that matter

An engagement ring, a camera kit, a good bike, a musical instrument, a watch that means something. Standard policies cap categories like jewelry at a sub-limit no matter how much total coverage you carry, so a valuable ring may be only partly covered.

Scheduling an item lists it individually at an agreed value, and on many policies it broadens coverage to include simply losing it. Bring us the appraisal or the receipt and we'll add it.

Already have a policy? Let us read it with you.

Replacement cost or cash value, liability limit, water backup, loss of use and sub-limits on the ring. A quick review, no charge and no pressure.

Six ways that may lower your price. On something already affordable.

The first one is the biggest: bundling with auto may lower what you pay on both policies. The rest are smaller, but they add up.

1

Bundle with your auto policy

A multi-policy discount can offset part of the renters premium, and one local agency handles both, with one phone call when something happens. Discounts vary by carrier, driver and address, so we shop the pair across several carriers and show you the actual numbers. Start with an auto quote and we'll price them together.

2

Choose a deductible you can actually cover

A higher deductible can trim the premium. On a policy this affordable the savings are modest, so only do it if you could pay that amount tomorrow without stress. Don't raise it past your emergency fund to save a few dollars a month.

3

Mention the building's safety features

Sprinklers, monitored alarms, smoke detectors, secured entry. Many apartment buildings have several of these and most renters never mention them. Tell us what your building has and we'll check which may qualify for a discount.

4

Ask about payment options

Paying in full can avoid installment fees with some carriers, and paperless or automatic payment options may earn a discount. We'll check what applies to your policy.

5

Think twice before filing a tiny claim

A loss that barely clears your deductible nets you very little and can stay on your record for years, following you to your next policy and eventually your homeowners policy. Call us first and we'll talk it through.

6

Don't under-insure to hit a price

Cutting your personal property limit to shave a few dollars isn't really saving. The point is that the policy is affordable enough to buy properly. We also won't talk you into limits you don't need.

However you rent. We'll help you cover it.

Apartment, house share, rental home, a student place near campus. The policy shifts to match.

An affordable way to protect everything you own.

One call, a few questions about your place and your stuff, and we'll shop it across several carriers. We can send proof of coverage to your landlord too.

Renters insurance across Ohio. From Marion to Columbus.

From apartments near Ohio State to rental homes in Delaware, Powell and Marion, renters rates move with your building and your neighborhood. Tell us the ZIP and we'll price your actual address. We serve renters across all of Ohio.

Ohio renters insurance questions. Straight answers.

Is renters insurance required in Ohio?

No state law requires it, but your lease very well might. Many apartment communities and property managers require a policy with a minimum liability limit and ask to be listed as an interested party.

Being listed as an interested party simply means the landlord is notified if your policy lapses. It doesn't give them coverage or let them file claims on your policy. If your lease requires renters insurance and you let it lapse, that can be a lease violation, so it's worth keeping current.

How much does renters insurance cost?

It's typically one of the most affordable policies you can buy. The price depends on your coverage amount, deductible, ZIP code, building and the carrier.

Bundling renters with your auto policy may lower what you pay. As an independent agency, we shop several carriers and show you the real numbers for your address.

What does renters insurance actually cover?

Four things. Personal property, meaning your belongings, wherever they are. Loss of use, which pays for somewhere to live if your unit becomes unlivable after a covered loss. Personal liability, which covers you if you injure someone or damage someone else's property, including legal defense. And medical payments for a guest's minor injuries.

Covered causes on most policies include fire and smoke, theft, vandalism, wind and hail, and most sudden water damage from inside the building. What it doesn't cover: the building itself, which is your landlord's job, flood, which is written separately, and sewer or sump backup unless you add a water backup endorsement.

Doesn't my landlord's insurance cover me?

No, and this is the most common misunderstanding in renting. Your landlord's policy covers the building: walls, roof, plumbing and common areas. It covers their property, not your life inside it.

If a kitchen fire in the unit above yours destroys everything you own, the landlord's insurance rebuilds the walls and replaces nothing of yours. Your furniture, laptop, clothes and the hotel you're now staying in are yours to pay for, unless you have your own policy.

Does renters insurance cover my roommate?

Generally no. A standard policy covers the named insured and a spouse or domestic partner. A roommate you aren't related to or partnered with isn't covered by your policy, even if you share the lease and the rent.

Each roommate needs their own policy. Separate policies mean separate limits, separate deductibles and no argument about whose claim used up the coverage. If you own your unit rather than rent it, you need condo insurance instead.

Does renters insurance cover storm, hail or tornado damage?

Generally yes, for your belongings. Wind and hail are covered causes on most renters policies. If a spring or summer thunderstorm sends hail or a tree limb through your window, or a tornado damages your building, the policy can pay to replace your damaged things. Loss of use applies if covered damage makes your unit unlivable.

Two things it doesn't do: repair the building, which is your landlord's policy, or fix hail damage on your car, which is comprehensive coverage on your auto policy. Water that rises from outside after the storm is flood, which needs a separate policy.

Does renters insurance cover a sewer backup or sump pump failure?

Usually not, unless you add a water backup endorsement. Water that backs up through a floor drain from the sewer, or seeps in because a sump pump failed, is generally excluded from standard renters policies.

In Ohio, where many homes and buildings have basements and sump pumps, this matters. If you rent a basement or garden-level unit, or keep belongings in a basement storage area, ask us to add water backup coverage. It isn't the same as flood coverage, and it isn't something your landlord's policy will pay for on your belongings.

Does renters insurance cover flooding?

No. Rising water from outside is excluded, whether it comes from a creek, a river or the street. Heavy rain can push waterways like the Olentangy River, the Scioto River and Alum Creek out of their banks, and low-lying units can take on water quickly.

A contents-only flood policy may be available for renters, because you're insuring belongings rather than a building. NFIP policies generally have a 30-day waiting period, so buy before storm season, not during it. Water from inside the building, like a burst pipe or the upstairs neighbor's overflowing tub, is sudden accidental damage and is generally covered by a standard policy.

Does renters insurance cover a burst pipe during a freeze?

Generally yes, for your belongings. When a pipe bursts suddenly during an Ohio cold snap, water damage to your things is typically a covered sudden and accidental loss, and loss of use can apply if the unit becomes unlivable. The pipe and the building are your landlord's to repair.

Policies expect reasonable care, so during a freeze keep the heat on, drip faucets if your landlord asks and report problems right away. If water from your unit damages a neighbor's and you're found responsible, your liability coverage may respond.

Does renters insurance cover my stuff stolen from my car?

Yes, and this catches people by surprise. Your auto insurance covers the car. It doesn't cover what was inside it. A laptop taken in a break-in is a renters claim, not an auto claim, and it's covered under personal property minus your deductible.

That coverage follows your belongings almost everywhere: a stolen bike outside class, luggage taken on vacation, a laptop lifted from a coffee shop.

How much personal property coverage do I need?

Probably more than you think. Walk through your place and add up what it would cost to replace everything at today's prices, not what you paid. Furniture, every screen, kitchen equipment, clothes, bikes, tools, instruments. Most people underestimate on the first pass.

Watch the sub-limits. Categories like jewelry, watches, firearms and collectibles are usually capped regardless of your overall limit. An engagement ring worth more than the cap should be scheduled separately.

What's the difference between replacement cost and actual cash value?

Replacement cost pays what it takes to buy a new equivalent today. Actual cash value pays what your stuff is worth used, after depreciation. For example, an older laptop might be worth $300 used but cost $1,400 to replace.

Replacement cost usually costs a bit more and can make a big difference at claim time. If your current policy pays actual cash value, that's the first thing we'd look at.

I'm an Ohio State student. Do I need my own policy?

Often, yes. Some parents' homeowners policies extend limited coverage to a student living away at school, but it varies by policy and may not include liability for your apartment. An off-campus lease will likely ask for a policy anyway.

A renters policy in your own name keeps your coverage clear, and if you have a car at school, bundling it with your auto policy may lower what you pay. Call and we'll check what makes sense for your situation.

Can you send proof of insurance to my landlord?

Yes. We can add your landlord or property manager as an interested party, which is what most leases ask for, and send proof of coverage directly to them.

If you're signing a lease soon and need proof before you get your keys, call and let us know your timeline. Our office hours are Monday through Friday, 9:00 AM to 5:00 PM Eastern.

Why use an independent agency for renters insurance?

Because we work for you, not an insurance company. eGoodwin Insurance represents multiple carriers, so we shop your renters coverage across several of them and compare, instead of offering one company's price.

We've served Ohio since 1990 from offices in Marion and Powell, and we're rated 5.0 on Google (88 reviews). Call (740) 387-8335 and we'll help you find the right fit.

Still have questions? Call (740) 387-8335. We'll give you a straight answer.

Protect everything you own.
Shopped across several carriers.

Tell us where you live and roughly what's in it. We'll compare quotes, look at bundling with your car and send proof of coverage to your landlord.