Home / Business / Business Property

Business Property Insurance in Ohio: Your building, your gear and the income behind it.

Coverage for the space you work in, what fills it and the income you lose if a covered loss shuts you down. We're an independent agency in Marion and Powell, so we compare several insurance companies for you.

1990Licensed Since
5.0On Google (88 Reviews)
MultipleCarriers Compared
2Ohio Offices
A local business team standing outside their Ohio storefront
The Quick Answer

Business property insurance (commercial property) helps pay to repair or replace your building, contents, inventory and equipment after a covered loss like fire, theft, vandalism or storm damage. Business income and extra expense coverage can help replace lost income and pay the added cost of staying open while repairs happen. Common additions include equipment breakdown and a sewer or water backup endorsement. Flood is generally excluded and needs separate coverage. How you insure it, at replacement cost or actual cash value, changes what a claim pays. eGoodwin Insurance is an independent agency in Marion and Powell that compares multiple carriers. Call (740) 387-8335.

Covers
Building, contents, inventory, equipment
Often added
Business income, equipment breakdown, backup
Not included
Flood (written separately)
Call first
(740) 387-8335
Business Property, The Short Version

Insuring the building is only half of it. The other half is what happens next.

Most business owners think about the walls and the roof. That matters, but a fire, a burst pipe or a hailstorm hits more than the structure. It hits your computers, your files, your stock, the equipment you depend on, and the income you were counting on while the doors are closed.

Business property insurance is built to handle all of that together. It can cover a building you own, the improvements you made to a space you lease, and the business personal property inside: furniture, computers, supplies, inventory, equipment and important papers. Paired with business income coverage, it can help keep the business going while the repairs get done.

We're an independent agency, so we shop your property coverage across several insurance companies and walk you through what comes back. Mark Goodwin has been a licensed insurance professional since 1990, and our offices in Marion and Powell work with businesses throughout Ohio. Our first question is usually simple: is your business personal property limit really enough?
What business property coverage can include. Building to backup.

Policies vary by carrier and form. These are the pieces we look at for most Ohio businesses, and the ones we'll check on your current policy.

Core
Building

The Building

The structure you own, plus permanent fixtures and systems. If you lease, the improvements you paid for, like build-outs and finishes, may need their own limit. Your lease usually says who insures what.

Core
Contents

Business Personal Property

Furniture, computers, supplies, tools, records and the other things that make the business run. This is the limit people most often underestimate, so we walk the space with you, at least on paper.

Core
Inventory

Inventory & Stock

Goods you sell or materials you use. If your stock swings with the season, ask about how the policy handles peak values so you aren't short at the busiest time of year.

Core
Income

Business Income & Extra Expense

Business income can help replace lost profit and pay ongoing costs like rent and payroll while a covered loss is repaired. Extra expense can help pay the added cost of staying open, like a temporary location.

Often added
Breakdown

Equipment Breakdown

A standard property policy may not cover the sudden mechanical or electrical failure of things like HVAC, refrigeration, boilers or specialized equipment. Equipment breakdown coverage is usually added for that.

Ohio basements
Backup

Sewer & Water Backup

Water that backs up through a drain or a failed sump pump is often excluded unless you add a backup endorsement. If you have a basement or lower level, this is worth a look.

Ask us
Valuation

Replacement Cost vs. ACV

Replacement cost pays to replace with new, similar property. Actual cash value subtracts depreciation, so an older roof or older equipment pays out less. The choice changes the premium and the check.

Ohio weather
Weather

Wind, Hail & Freeze

Ohio sees spring and summer thunderstorms, hail, straight-line winds and the occasional tornado, then winter freezes that burst pipes. Some policies carry a separate wind/hail deductible, so we'll show you yours.

Not covered
Flood

Flood

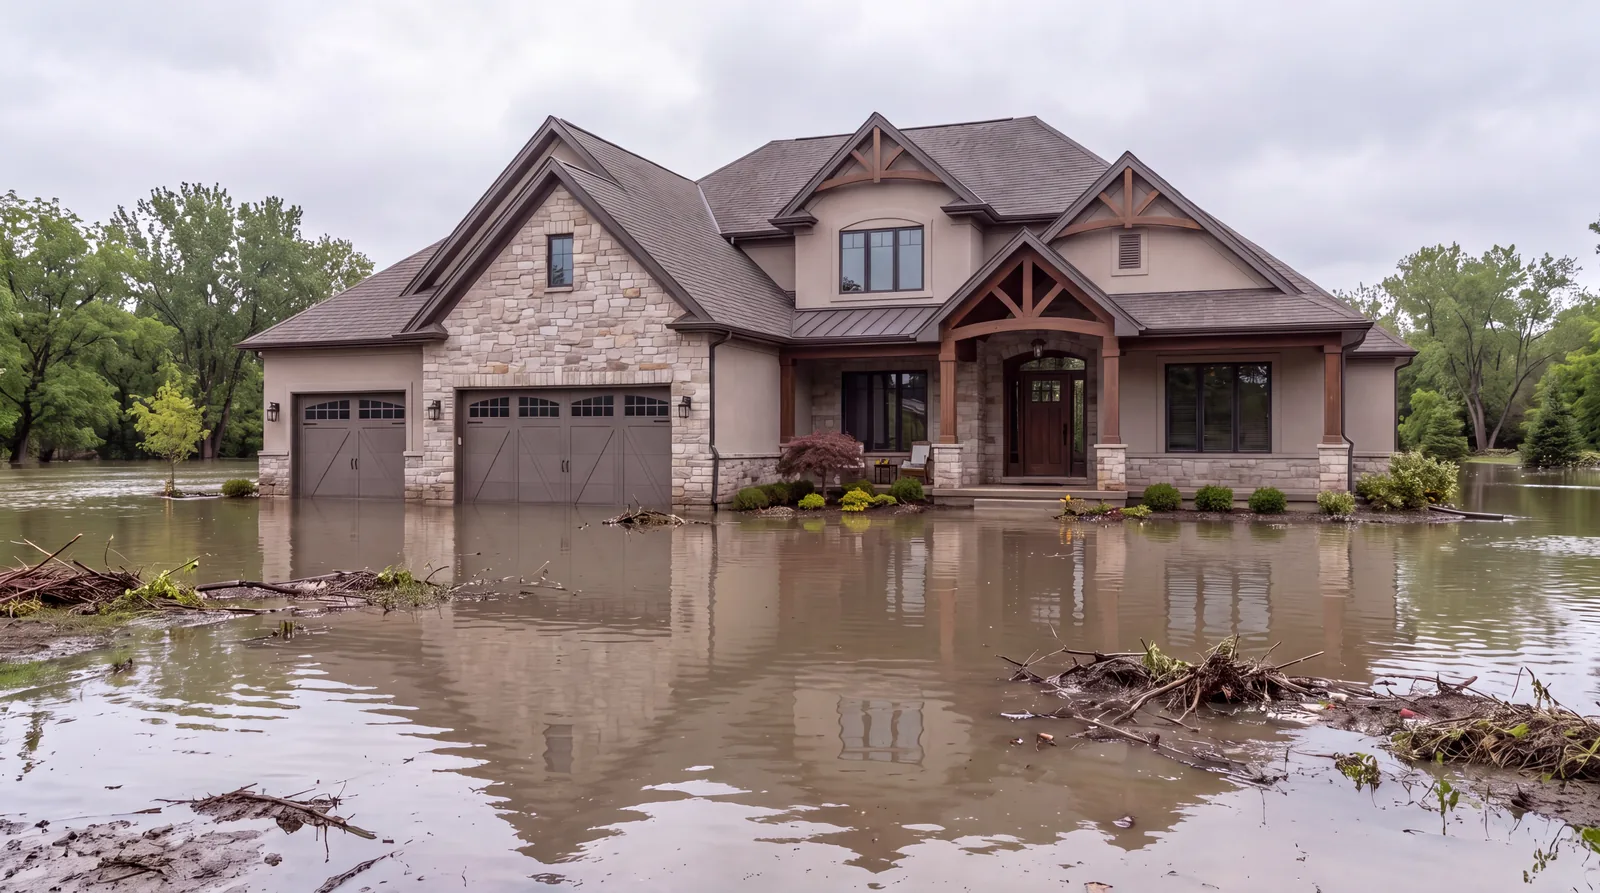
Flood is generally excluded from business property policies. It's written separately. If you're near the Olentangy or Scioto River or a creek that rises in heavy rain, see our flood insurance page.

Is your contents limit still right?

New equipment, more inventory, a remodel or a second location can all leave an old limit behind. Send us what you have and we'll compare it with what you own today. Free review.

Who needs business property coverage. Nearly everyone with a door.

If your business owns a building, leases a space or keeps equipment and stock anywhere, property coverage is part of the program.

How It Fits

Property is one piece. Here's how it fits with the rest.

Inside a Business Owners Policy

Many small businesses get property coverage through a Business Owners Policy (BOP), which packages commercial property, general liability and business income. Larger buildings, higher values or special risks may need a standalone commercial property policy instead. See our business insurance overview for the full picture.

Flood is separate

Flood is generally excluded from business property policies. Flood coverage is usually written on its own, and many flood policies carry a waiting period before coverage starts, so don't wait for a storm in the forecast. Our flood insurance page explains more.

Equipment on the move

Property policies focus on what stays at your location. Equipment and tools that travel are often better covered under inland marine.

Liability sits beside it

Property pays for your things. Liability pays when someone else claims you hurt them or damaged their property. Most businesses need both, and many add a commercial umbrella on top of the liability side.

Business property questions. Straight answers.

What does business property insurance cover?

It can cover your building if you own it, plus business personal property like furniture, computers, supplies, inventory, equipment and records, against covered causes of loss such as fire, theft, vandalism and many kinds of storm damage.

Many policies can also include business income and extra expense, which help with lost income and added costs while repairs happen. Exact coverage depends on the policy form and carrier.

I lease my space. Do I still need property insurance?

Usually, yes. Your landlord's policy generally covers the building, not your furniture, equipment, inventory or the improvements you paid for.

Your lease often spells out what you're responsible for insuring. Send it to us and we'll match your coverage to it.

What is business income coverage?

After a covered loss forces you to slow down or close, business income coverage can help replace lost profit and pay ongoing expenses like rent and payroll during the repair period.

Extra expense coverage can help pay the added cost of staying open, like renting temporary space. Policies have limits and waiting periods, so we'll walk through how yours works.

What's the difference between replacement cost and actual cash value?

Replacement cost pays what it costs to replace damaged property with new property of similar kind and quality. Actual cash value subtracts depreciation, so older items pay out less.

Replacement cost usually costs more up front but can mean a much smaller gap after a claim. Some policies also require you to carry a minimum percentage of the property's value, so we'll check your limits too.

Does business property insurance cover flood?

Generally, no. Flood is excluded from most business property policies and is written separately.

If you're near the Olentangy or Scioto River or a creek that rises in heavy rain, ask us about flood coverage. Many flood policies have a waiting period, so it's best not to wait.

Is sewer or drain backup covered?

Often not, unless you add a water or sewer backup endorsement. Water that backs up through a drain or comes in when a sump pump fails is a common exclusion.

If your building has a basement or lower level, this is one of the first things we'll check.

What is equipment breakdown coverage?

It can cover sudden mechanical or electrical breakdown of equipment like HVAC systems, boilers, refrigeration, computers and specialized machines, which a standard property policy may not cover.

It can also include the income you lose while that equipment is down, depending on the policy. For practices and restaurants, it's usually worth a look.

How much does business property insurance cost?

It depends on the building, its construction and age, what's inside, your location, your deductible, how you value the property and your claims history. There isn't one honest number for every business.

Because we're an independent agency, we shop your coverage across several carriers and compare. Call us and we'll quote your actual property.

Still have questions? Call (740) 387-8335. We'll give you a straight answer.

Tell us what's inside.
We'll help you insure all of it.

Your building, your equipment, your inventory and the income behind it. We'll check your limits, shop your coverage across several carriers and explain the trade-offs in plain English.